
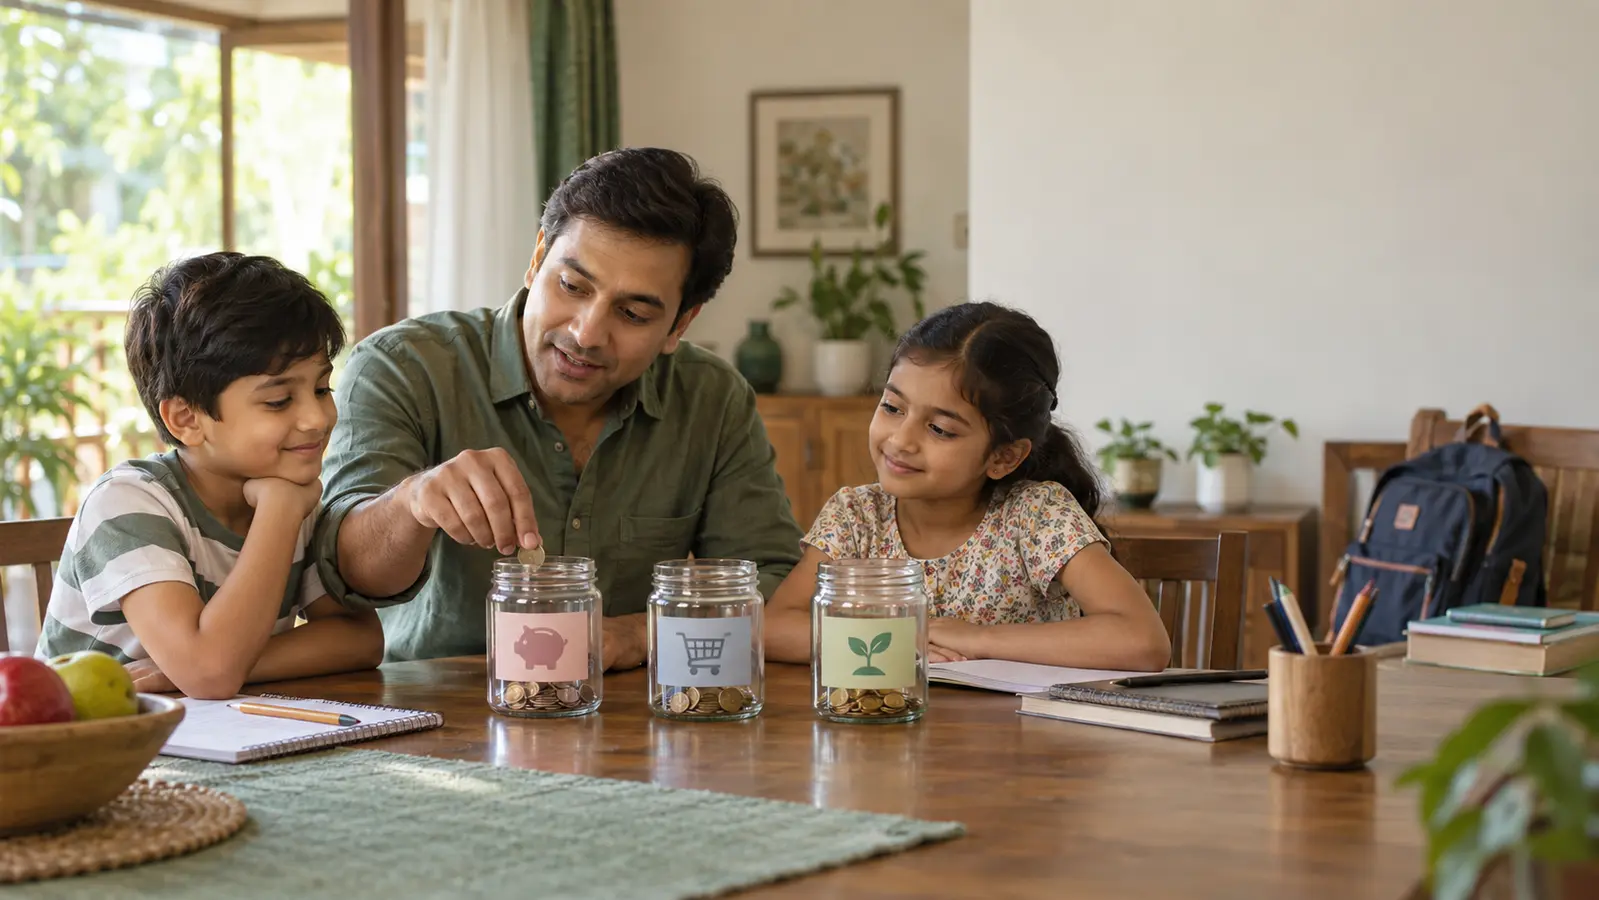
On Teachers’ Day, we celebrate the people who shape how children think. But one subject is often taught only through observation: money.
Children notice when parents compare prices, pay by UPI, discuss an EMI, postpone a purchase or worry about an unexpected bill. Long before they earn their first salary, they are already forming beliefs about spending, saving and wealth.
That makes financial education important. But it should not begin with stock tips, mutual-fund rankings or a lesson on how to maximise returns. Those are product decisions. A child first needs a sound way to think about money.
This broader approach is consistent with India’s financial-education framework. The Reserve Bank of India’s financial-education initiative covers good financial practices, digital safety and consumer protection, while SEBI’s investor-education material begins with saving, budgeting, financial goals, debt management and insurance before investment products.
Lesson 1: Money Is Limited, So Every Choice Has a Trade-off
A child may see a ₹500 purchase simply as something the family can or cannot afford. The deeper lesson is that using ₹500 for one purpose means it is no longer available for another.
This is the idea of a trade-off. It is more useful than repeatedly telling children that something is “too expensive” or that they should never spend on wants.
Begin with three simple categories:
- Needs: essential expenses such as food, basic clothing, school requirements and healthcare.
- Wants: enjoyable but optional expenses such as a new game, eating out or an upgraded gadget.
- Goals: something meaningful that requires money to be set aside over time.
The categories are not always rigid. A phone may be necessary for an older student, while the most expensive model is a preference. The purpose is not to judge every purchase. It is to teach children to ask, “What am I giving up if I choose this?”
Lesson 2: Predictable Expenses Should Be Planned, Not Treated as Emergencies
Many family expenses do not arise every month, but they are not surprises. School fees, uniforms, annual insurance premiums, vehicle renewals, extracurricular fees and planned travel may be due only once or twice a year.
A child can learn an important financial-planning principle from these expenses: frequency does not determine predictability.
Suppose a school-related expense of ₹12,000 will be due after twelve months. Instead of waiting for the due date and disturbing that month’s cash flow, the family can set aside ₹1,000 each month. The amount has not been reduced, but its impact has been spread across the year.
This also helps distinguish an annual expense from a genuine emergency. A known premium due date is predictable. An unexpected hospital visit is not. Both require money, but they need different financial buckets.
Parents do not need to disclose every detail of the household budget. A simple example is enough:
- identify the future expense;
- note when it will be due;
- divide the target by the number of months available; and
- set aside the amount before spending what remains.
This is one of the earliest forms of goal planning. It teaches that saving is not merely whatever money happens to remain at month-end.
For a fuller family-level method, read Annual Expenses Are Not Emergencies: Plan for Them Monthly.
Lesson 3: An EMI Shows the Monthly Payment, Not the Total Cost
Children are growing up in a world where a product costing ₹60,000 may be advertised primarily through a much smaller monthly EMI. This can make borrowing appear to reduce the price. It does not.
An EMI divides repayment over time. Depending on the terms, the buyer may also pay interest, processing charges, taxes on charges or other costs. Even a genuine no-cost EMI can affect future monthly cash flow and limit the family’s choices until it ends.
The child does not need to calculate reducing-balance interest immediately. Start with three questions:
- What is the total amount that will be paid?
- For how many months will income already be committed?
- What happens if income falls or another important expense arises?
The lesson is not that all borrowing is wrong. A responsibly managed home or education loan may support an important family goal. The lesson is that borrowing uses future income and should be evaluated by purpose, affordability and total cost—not by the apparent convenience of one monthly number.
Lesson 4: Saving, Protection and Investing Have Different Jobs
Children often hear that they should “save and invest,” as if these were interchangeable. They are not.
- Saving keeps money available for near-term needs and planned expenses.
- Protection helps the family handle the financial impact of serious risks. Insurance is primarily a risk-management tool, not a guaranteed route to wealth creation.
- Investing accepts some uncertainty in pursuit of future growth for suitable goals and time horizons.
A higher potential return usually comes with some form of higher risk. The value may fluctuate, the outcome may differ from expectations, or the money may not be conveniently available when required. A child who understands this principle is better prepared than one who has merely memorised that a certain product “gives better returns.”
Compounding is worth teaching, but it should not be presented as magic. Time can help returns build on earlier returns, but actual outcomes depend on the investment, costs, taxes, behaviour and market conditions. Starting early is helpful; selecting a suitable approach and continuing sensibly also matter.
Lesson 5: Good Money Habits Develop Through Small Decisions
Financial literacy cannot be taught through one lecture. Children learn when they repeatedly make manageable decisions and see their consequences.
Pocket money can help, but it is not essential. Parents can involve children in comparison shopping, planning a small celebration, choosing between two outings or saving towards a book, sports item or hobby.
The responsibility should grow gradually with age:
| Stage | Useful concepts | Simple practice |
|---|---|---|
| Under 10 | Needs, wants, choices and waiting | Save for one small goal and compare two prices |
| 10–13 | Budgeting, planned expenses and basic interest | Plan a fixed amount across spending, saving and giving |
| 14–17 | Debt, risk, digital payments, fraud and investing basics | Review a sample EMI, identify scam warning signs and plan a longer goal |
These age bands are only guides. The right activity depends on the child’s maturity and the family’s circumstances.
Do Not Make Children Carry Adult Financial Anxiety
There is an important difference between financial education and transferring financial stress to a child.
Children can understand that the family has limits without being made responsible for a parent’s loan, medical costs or investment losses. Avoid statements that create guilt, such as suggesting that one ordinary request has damaged the household finances.
A healthier approach is factual and calm:
- “We have planned a certain amount for this.”
- “We can choose one of these options, but not both.”
- “This expense is due later, so we are setting money aside each month.”
- “This offer looks attractive, but we should first check the total cost.”
Children should also see adults correct mistakes. A parent who says, “We bought this too quickly; next time we will compare first,” may teach more than a perfect-looking budget ever could.
Digital Money Needs Digital Safety
Money can feel less real when it moves through a tap, QR code or in-app purchase. That makes digital safety part of basic financial education.
Children should know that:
- an OTP, PIN, password or card security code should not be shared;
- a request marked “urgent” is not automatically genuine;
- unknown links, screen-sharing requests and offers of easy money are warning signs;
- receiving money generally does not require entering a UPI PIN; and
- they should pause and ask a trusted adult before acting on a financial message.
The goal is not to make children fearful of digital payments. It is to build the habit of slowing down when someone tries to create urgency or secrecy.
A Simple Family Exercise for This Week
- What do we want to achieve?
- How much will it cost?
- When will we need the money?
- How much should we set aside regularly?
- What might make us change the plan?
This exercise contains the foundations of financial planning: a defined goal, a cost, a time horizon, regular saving and periodic review. No product recommendation is needed.
The Takeaway
The first financial lesson a child needs is not how to pick an investment. It is how to make a choice.
From there, parents can teach that known expenses deserve advance planning, an EMI is a claim on future income, insurance and investing perform different roles, and higher potential returns come with uncertainty.
These ideas will not guarantee that every future decision is perfect. They can, however, give children a framework for asking better questions. That is a far more durable advantage than an early tip about any particular financial product.
As the child grows, the family’s financial plan will become more complex. A qualified financial professional can help parents connect education funding, protection, retirement and investments without asking one product to solve every need.
Let’s discuss your family’s financial goals.
Frequently Asked Questions
At what age should parents begin teaching children about money?
Begin when a child starts making small choices. The lesson should match the child’s maturity: younger children can learn waiting and trade-offs, while older children can explore budgets, borrowing, digital safety and investment risk.
Should children receive pocket money?
Pocket money can provide useful practice when the amount, frequency and boundaries are clear. It is not essential; real family decisions and small goal-based exercises can teach the same principles.
Should a child be encouraged to invest early?
Understanding investing early can be useful, but product selection should not come before basic money habits. Any actual investment for a minor should be considered as part of the parents’ broader financial plan, with current guardian, KYC, account-operation and tax requirements verified before acting.
How can parents discuss money without making children anxious?
Discuss choices and plans in calm, age-appropriate terms without sharing burdens the child cannot control. Focus on what the family has decided to do rather than using guilt or fear to restrict spending.
What is the most important money habit for a child?
There is no single habit for every child, but pausing before a decision is an excellent foundation. It creates space to consider need, cost, alternatives, future consequences and risk.
Sources and Further Learning
- Ministry of Education: National Teachers’ Awards
- Press Information Bureau: National Teachers’ Awards on 5 September 2026
- Reserve Bank of India: Financial Education Initiative
- SEBI Investor: Money Matters
- SEBI Investor: Financial Education Material for School Children and Families
- National Centre for Financial Education: Money Smart School Programme
Disclaimer: This article is for education and awareness only. It is not investment, insurance, legal or tax advice and does not recommend any financial product. Rules relating to minor bank accounts, mutual-fund folios, guardianship, KYC and taxation can change; verify the latest requirements with the relevant institution or a qualified professional before acting. Mutual-fund investments are subject to market risks. Read all scheme-related documents carefully.