Quick answer: A large cap fund must keep most of its equity portfolio in India’s biggest listed companies. A flexi cap fund can move across large, mid and small companies. Neither category is automatically better. The more useful choice is the one that fits your goal, time horizon, risk capacity and existing investments.
Large cap and flexi cap funds are often considered for the core of an equity portfolio. At first glance, the difference seems simple: one focuses on large companies, while the other has more freedom. In practice, that freedom changes how the fund may behave, what risks it can take and how it may overlap with the rest of your portfolio.
Before comparing returns, it helps to understand what each category is designed to do.
What is a large cap mutual fund?
Under SEBI’s mutual-fund category framework, a large cap fund must invest at least 80% of its assets in large-cap stocks. Large-cap companies are generally the top 100 listed companies by full market capitalisation, based on the classification used for mutual funds.
This rule gives the category a fairly clear identity. Most of the portfolio remains in established businesses with large market values. These companies may have longer operating records, wider access to finance and more diversified businesses than smaller companies. That does not make their shares safe or immune to falls. Their prices can still decline because of high valuations, weak results, regulation or broad market stress.
A large cap fund can therefore provide focused exposure to the large-company part of the equity market. It may appeal to an investor who wants a relatively defined market-cap allocation instead of leaving that choice fully to the fund manager.
What is a flexi cap mutual fund?
A flexi cap fund must invest at least 65% of its assets in equity and equity-related instruments. Within its equity portfolio, the manager can invest across large-, mid- and small-cap companies without a fixed minimum allocation to each segment.
This freedom is the category’s main feature. A manager may hold a large-cap-heavy portfolio at one point and add more mid- or small-cap exposure when opportunities appear attractive. The actual mix depends on the scheme’s strategy, the manager’s decisions and market conditions.
Flexibility can help a manager look beyond one market-cap segment. It can also make the portfolio less predictable from its category name alone. Two flexi cap funds may have very different market-cap mixes, concentration levels and investment styles.
Large cap vs flexi cap: the main differences
| Feature | Large cap fund | Flexi cap fund |
|---|---|---|
| Core rule | At least 80% in large-cap stocks | At least 65% in equity and equity-related instruments |
| Market-cap freedom | Limited because most assets must remain in large caps | Manager can change the mix of large, mid and small caps |
| Portfolio predictability | The large-cap bias is clear from the category | The market-cap mix can change over time |
| Risk tendency | Usually less exposed to smaller-company risk, but still an equity fund | Risk can rise when mid- and small-cap exposure increases |
| Manager decision | Security selection matters, but the market-cap range is narrower | Both security selection and market-cap allocation matter |
| Possible portfolio role | A defined large-company equity allocation | A diversified equity allocation with manager flexibility |
The table describes category rules, not a promise about outcomes. A flexi cap fund may sometimes resemble a large cap fund if it holds mostly large companies. A large cap fund can still be concentrated in a few sectors or stocks. The scheme’s current portfolio matters as much as its label.
How might they behave across market cycles?
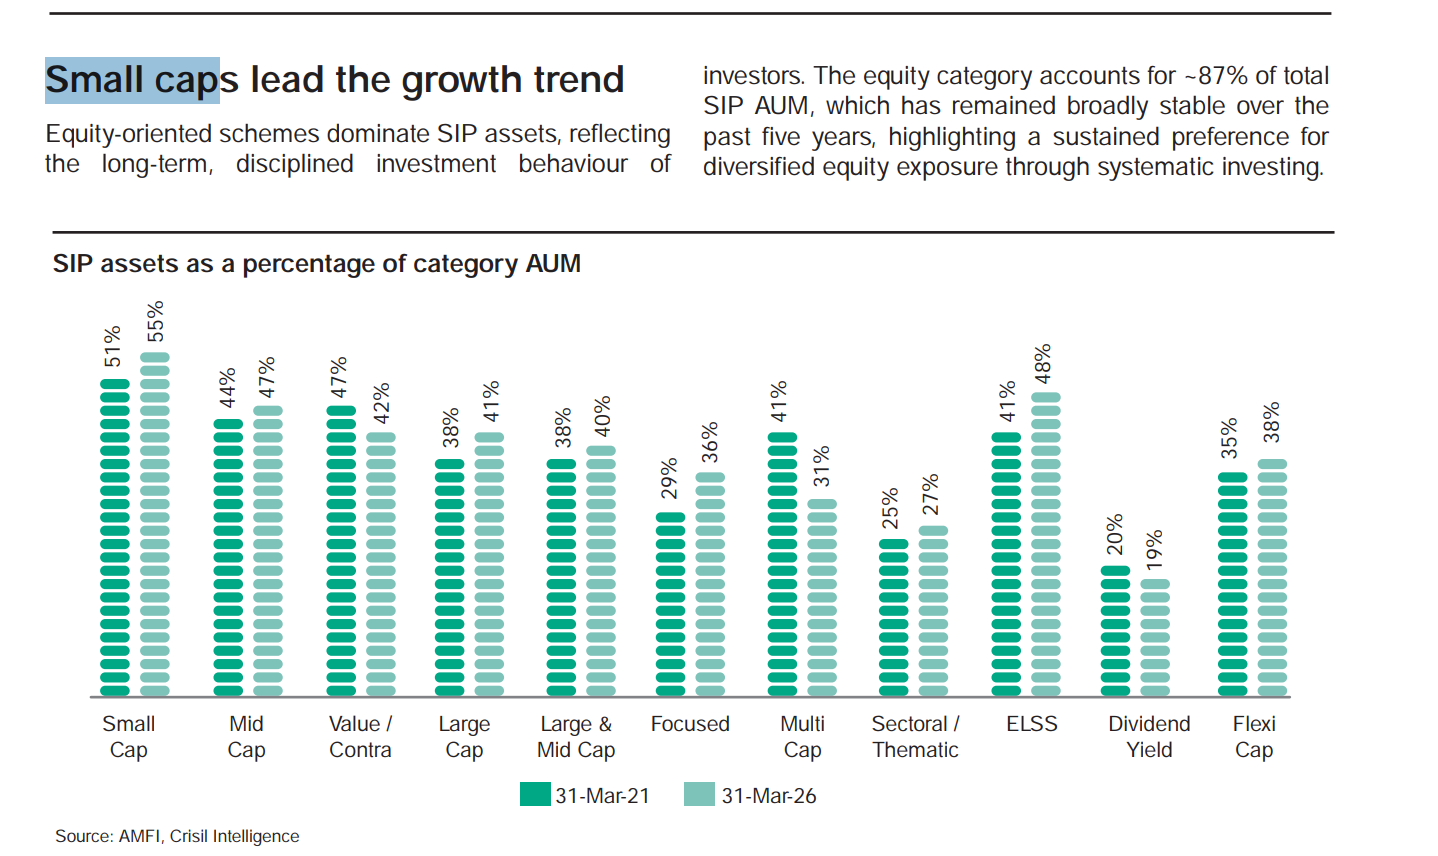
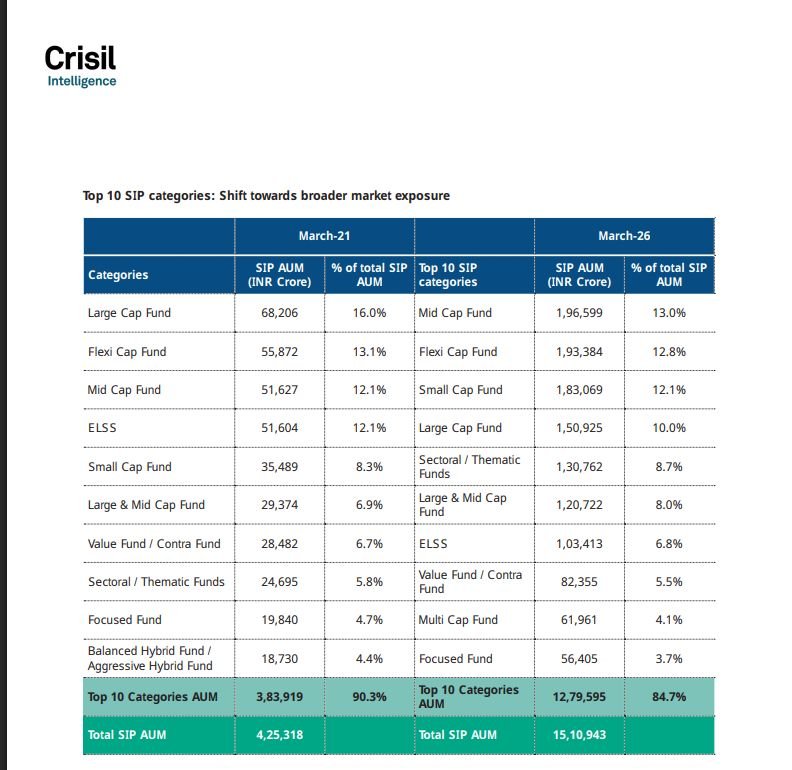
Large-cap shares and smaller-company shares do not lead the market at the same time. When mid and small caps are rising strongly, a flexi cap fund with meaningful exposure to them may benefit. It may also fall more sharply if sentiment reverses. A flexi cap manager can reduce smaller-company exposure, but there is no guarantee that every shift will be timely or successful.
A large cap fund stays closer to its defined segment. Its returns may therefore lag a broad rally led by smaller companies. It can also avoid taking a large direct exposure to that part of the market. This does not mean large cap funds always fall less. Portfolio concentration, valuations and business conditions can produce different results.
Recent performance should not decide the category. The winner of the last one or three years may simply reflect which market segment was in favour. Your holding period is likely to include several such phases.
Is a flexi cap fund always more diversified?
No. Permission to invest across market caps does not ensure broad diversification. A flexi cap scheme may still hold a high share in large caps, a small number of stocks or a few sectors. Another scheme may spread its portfolio much more widely.
Before investing, look at the latest factsheet. Check the market-cap split, top holdings, sector weights and number of stocks. Also review whether the portfolio has changed sharply. The aim is not to find a fund that never changes. It is to understand the kind of flexibility you are accepting.
Can you hold both large cap and flexi cap funds?
You can, but the combination needs a reason. Buying one of each does not automatically improve diversification.
Suppose your flexi cap fund already keeps most of its money in large companies. Adding a large cap fund may increase exposure to the same leading stocks and sectors. You may then own two schemes without gaining a meaningfully different portfolio.
Holding both may make sense when the large cap allocation has a defined role and the flexi cap fund brings a genuinely different strategy. Review the combined holdings and their weights. SEBI’s 2026 category framework has also strengthened the focus on schemes remaining true to their labels and on portfolio-overlap disclosures. Investors should still examine overlap at their own full-portfolio level.
If you are comparing flexi cap with another diversified category, our guide to multi cap vs flexi cap funds explains how a fixed market-cap allocation differs from manager flexibility.
Which category may fit your portfolio?
A large cap fund may be considered when you want a clear allocation to established large companies and already have mid- and small-cap exposure elsewhere. It may also suit a plan in which each market-cap segment has a separate, deliberate weight.
A flexi cap fund may be considered when you want one equity scheme that can invest across company sizes. It can suit investors who are comfortable allowing the manager to change that mix. You still need enough time to tolerate equity-market falls.
Neither category is suitable merely because it has recently performed well. Money needed soon or on a fixed date may require assets with lower volatility. Your equity allocation should reflect the entire family balance sheet, including EPF, PPF, NPS, deposits, property, debt and other mutual funds.
For a broader view of the risk differences between company sizes, read our guide to large cap, mid cap and small cap funds. Your ability to stay invested during a fall also matters, as explained in our article on matching investments to your risk profile.
A practical checklist before you invest
- Define the goal: State what the money is for and when it will be needed.
- Set the equity allocation: Decide how much risk the goal and family finances can support.
- Identify the category’s job: Choose whether you need a fixed large-cap exposure or a manager-led market-cap mix.
- Inspect the actual portfolio: Review market-cap split, sectors, concentration and overlap with funds you already own.
- Study consistency: Look beyond recent returns to the scheme’s process, portfolio changes, risk and performance across market phases.
- Keep the structure simple: Add a fund only when it performs a distinct role.
- Review periodically: Rebalance when your goal, allocation or fund role changes—not because of short-term rankings.
The current SEBI category framework is a useful starting point for understanding scheme labels. The regulator’s flexi cap circular explains the category’s equity requirement and flexibility across market capitalisations. A label narrows the search, but it cannot decide suitability on its own.
The choice is about portfolio design, not a winner
Large cap funds offer a more defined exposure to India’s largest listed companies. Flexi cap funds give the manager more room to search across company sizes. That flexibility may be useful, but it also makes the manager’s allocation decisions more important.
Start with the role you need. Then check whether the actual scheme and its portfolio fulfil that role without unnecessary duplication. A financial plan should guide the fund choice—not the other way around.
Disclaimer: This article is for general educational purposes and is not a recommendation to buy, sell or hold any mutual-fund scheme or security. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully and consider your goals, risk profile and complete financial position before investing.