Investors often begin with a product question:
Which mutual fund should I invest in?
A better starting point is:
How much of this money can take market risk, and when will the family need it?
That is the purpose of asset allocation.
Asset allocation decides how money is divided among equity, fixed income, cash, gold and other assets. SEBI notes that this decision should reflect the investor’s goals, risk tolerance and time horizon.
The right allocation therefore cannot be determined by age or investor temperament alone.
What does asset allocation mean?
Each asset class has a different job.
- Equity may support long-term growth but can fall sharply.
- Fixed income may provide greater stability, but it still carries interest-rate, credit, reinvestment and inflation risks.
- Cash and near-cash assets provide access for emergencies and near-term payments.
- Gold may provide diversification, but its price can also fluctuate.
- Other assets may include real estate, international investments, REITs and similar holdings.
Asset allocation brings these parts together. It is not simply a decision between equity and debt. It is a plan for deciding which risks the family can accept for each goal.
Asset allocation and diversification are not the same
The two ideas are related, but they solve different problems.
| Asset allocation | Diversification |
|---|---|
| Divides money among different asset classes | Spreads exposure within or across those asset classes |
| Example: equity, fixed income, cash and gold | Example: several industries and companies within equity |
| Sets the portfolio’s broad risk structure | Reduces dependence on one security, sector or strategy |
Owning six equity funds may provide some diversification. But it does not create a balanced asset allocation if the entire portfolio is still exposed to equity-market movements.
AMFI also explains that diversification can extend across securities and asset categories such as equity, debt and gold.
One family may need several allocations
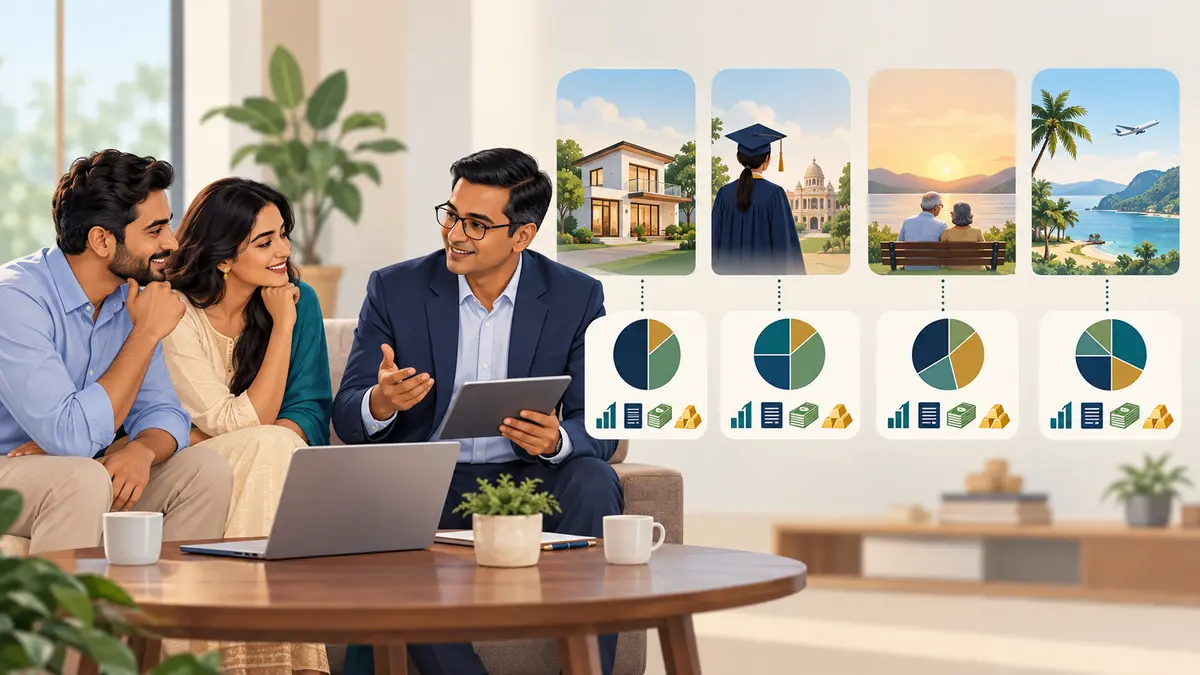
A family rarely has only one goal. It may simultaneously be preparing for next year’s school fees, a home purchase in four years, a child’s higher education in ten years and retirement after twenty years.
These goals should not automatically share the same allocation.
| Goal situation | Main planning priority |
|---|---|
| Money needed soon | Access and stability matter more than maximising return |
| Goal several years away | Balance growth needs with the ability to withstand fluctuations |
| Long-term goal | Growth assets may have a larger role, supported by diversification |
| Goal approaching | Gradually reduce dependence on a favourable market at the withdrawal date |
These are planning principles, not fixed allocation rules.
A family’s suitable mix also depends on income stability, liabilities, existing assets, flexibility of the goal and the consequences of a shortfall.
SEBI’s goal planner separately considers the time remaining, existing equity and fixed-income assets, inflation, expected post-tax returns and the allocation used for each goal.
Investor temperament cannot decide the allocation by itself
Someone may be emotionally comfortable with market falls and describe themselves as aggressive. That does not mean money required next year should be invested aggressively.
Three different questions must be considered:
- Risk willingness: How does the investor react when investments fall?
- Risk capacity: Can the family financially afford the decline?
- Risk required: How much risk, if any, is needed to fund the goal?
A person may have high risk willingness but low capacity because of unstable income, large commitments or a goal that is close.
The reverse is also possible. A family may have strong finances and a long horizon but remain uncomfortable with market fluctuations. An allocation that causes panic-driven exits may not be sustainable.
Count the family’s existing assets
Asset allocation should not begin only with new mutual-fund investments.
Indian families may already hold substantial amounts in EPF, PPF, NPS, bank deposits, traditional policies, gold, direct shares, mutual funds and property.
EPF, PPF and deposits generally form part of the family’s fixed-income allocation. Ignoring them can produce an incomplete picture.
Similarly, an equity portfolio spread across mutual funds, direct shares and NPS equity does not become less concentrated merely because it is held on different platforms.
A residential home may be part of net worth, but it may not be available to fund every financial goal. Asset allocation should distinguish between total net worth and assets that can realistically be used for the goal.
A fund category is not an asset-allocation plan
Selecting a large-cap, flexi-cap or hybrid fund is a product decision. Asset allocation comes before that decision.
The sequence should ordinarily be:
- Define the goal and target date.
- Estimate its future cost.
- Identify existing assets assigned to it.
- Decide the broad mix of assets.
- Select suitable products within each part.
- Review progress and reduce risk when required.
Starting with a popular fund can reverse this order. The investor may accumulate products first and attempt to invent a portfolio later.
Common asset-allocation mistakes
1. Choosing the allocation from recent returns
After equity performs well, investors may increase equity because it feels safe. After a fall, the same investors may reduce it because it feels risky. This can result in buying after gains and selling after declines.
2. Using one allocation for every goal
A retirement goal twenty years away and a payment due in two years should not depend on the same market outcome.
3. Assuming more equity guarantees the target
A higher equity allocation increases uncertainty. It may improve long-term return potential, but it cannot guarantee the required corpus.
SEBI’s asset-allocation calculator specifically warns that higher equity should not be naively assumed to produce a higher return. It also states that its calculations are illustrative because market returns cannot be predicted.
4. Ignoring tax and access
Two assets with similar expected returns may differ in liquidity, taxation, lock-in and withdrawal rules. The most suitable asset is not always the one with the highest expected return.
5. Never reviewing the allocation
Market movements can change the portfolio. For example, a planned allocation may become equity-heavy after a strong market rise. The family’s goals may also change because of a new loan, job change or approaching expense.
What is rebalancing?
Rebalancing brings the portfolio back towards its planned mix.
This may be done by:
- directing new investments towards the underweight asset;
- using withdrawals or maturity proceeds;
- reducing an overweight allocation; or
- changing future contributions instead of selling immediately.
Rebalancing is not a return-enhancement trick. Its main purpose is to keep the portfolio’s risk aligned with the plan.
Before redeeming or switching, check capital-gains taxation, exit loads, lock-ins and product terms. SEBI also recommends reviewing investments and rebalancing when the mix is no longer aligned with the investor’s objectives.
How guidance can help
A suitable allocation cannot be copied from a model portfolio without context.
A financial professional can help connect:
- the family’s complete balance sheet;
- each goal’s importance and timeline;
- existing EPF, PPF, NPS and other assets;
- cash-flow commitments;
- risk capacity and temperament;
- tax and liquidity requirements; and
- a planned reduction in risk as goals approach.
The objective is not to forecast which asset will perform best next year. It is to build a structure in which one poor market period does not unnecessarily disrupt an important family goal.
The takeaway
Asset allocation answers a more important question than “Which fund is best?”
What mix of assets gives this particular goal a reasonable balance of growth, stability and access?
One family may need different allocations for different goals. The mix should reflect the goal’s date, importance, existing funding and the family’s ability to handle uncertainty.
Products should be selected only after this structure is clear.
Related reading
- Conservative, Moderate or Aggressive Investor?
- How Should Your Investing Approach Change?
- Debt Mutual Funds: Why Your Goal Matters
- Large Cap vs Mid Cap vs Small Cap Funds
Sources
- SEBI Investor: Things to consider before investing
- SEBI Investor: Asset Allocation Calculator
- SEBI Investor: Financial Goal Planner
- AMFI: Advantages of investing in mutual funds
Disclaimer: This article is for educational purposes only and does not constitute investment, tax, legal or financial advice. The suitable asset allocation depends on the investor’s complete financial position, goals, time horizon, liquidity needs and risk profile. Market-linked investments can fluctuate, and past performance does not guarantee future results. Tax rules, exit loads and product terms should be verified before making a transaction.