
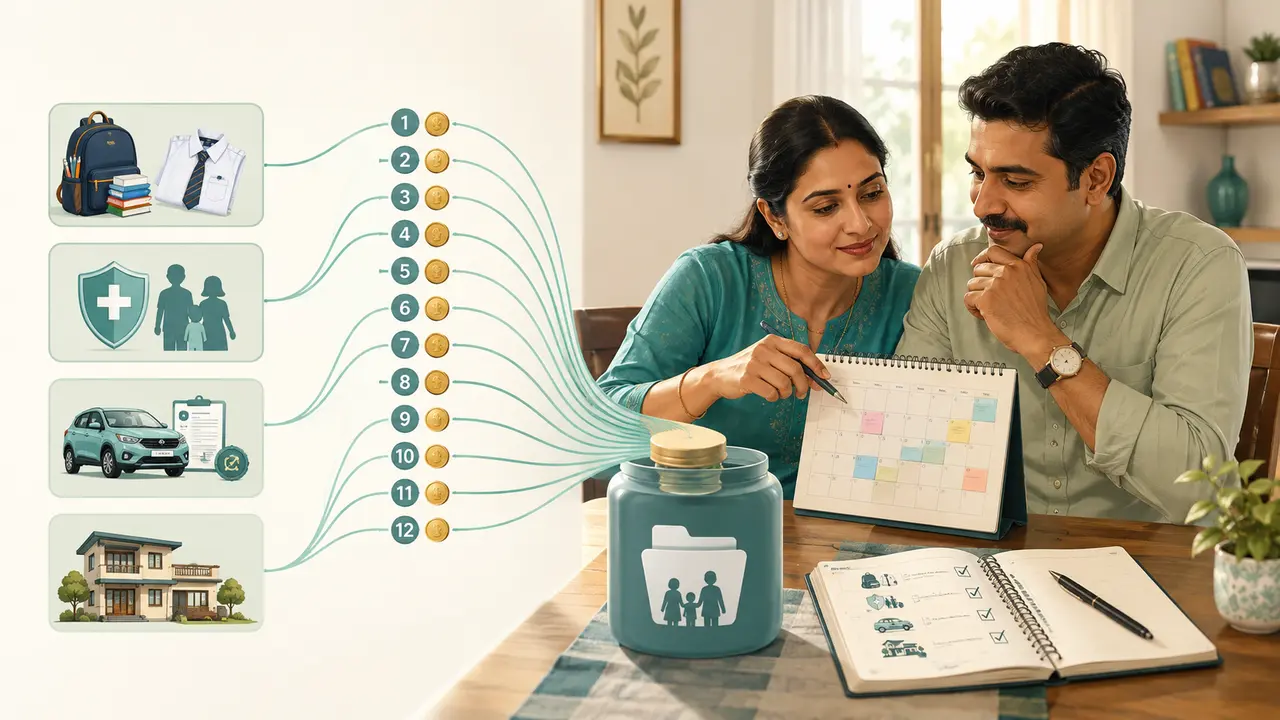
School fees may be due once a term. A life-insurance premium may be paid once a year. Uniforms and books are usually purchased before the new academic year, while vehicle insurance and property-related payments have their own renewal dates.
These bills do not occur every month, but they are not unexpected.
The problem begins when a family treats them as surprises. A large payment then has to come from that month’s salary, a credit card, the emergency fund or even money meant for a SIP. The expense itself may be unavoidable, but the financial pressure is often avoidable.
The solution is to convert predictable annual expenses into a monthly commitment.
Predictable does not always mean fixed
Some annual expenses are known exactly in advance, such as an insurance-renewal premium. Others, including school fees, books, uniforms, property tax and vehicle maintenance, may increase from year to year.
It is therefore more useful to call them predictable expenses rather than strictly fixed expenses. We may not know the exact amount, but we usually know:
- The expense will occur
- Approximately when it will be due
- Roughly how much it may cost
That is enough information to begin planning.
Common annual expenses for an Indian family
Every household will have a different list. The following table can be used as a starting point.
| Expense | Likely frequency | What to estimate |
|---|---|---|
| School or college fees | Term-wise or annually | Fees plus the expected annual increase |
| Books, uniforms and school transport deposits | Once or twice a year | Previous year’s spending with a buffer |
| Life and health-insurance premiums | Monthly, quarterly or annually | Premium and renewal date for each policy |
| Motor insurance and vehicle servicing | Annual or periodic | Renewal, regular service and known replacements |
| Property tax and annual maintenance | Half-yearly or annually | Latest bill and expected revision |
| Professional, club and digital subscriptions | Annual | Only the renewals you intend to keep |
This is not a list of expenses that must be reduced. School fees or a valid insurance premium may be necessary commitments. The purpose of the exercise is to make sure the money is available when the payment is due.
Convert the yearly total into a monthly amount
Start with bills and bank statements from the previous year. List each predictable expense, its expected amount and its due month. Add a reasonable increase wherever the cost is likely to rise.
Here is an illustrative example:
| Expense | Estimated annual amount | Monthly provision |
|---|---|---|
| School fees | ₹60,000 | ₹5,000 |
| Books and uniforms | ₹12,000 | ₹1,000 |
| Life-insurance premiums | ₹30,000 | ₹2,500 |
| Health and motor insurance | ₹36,000 | ₹3,000 |
| Property and vehicle-related payments | ₹18,000 | ₹1,500 |
| Other planned annual renewals | ₹12,000 | ₹1,000 |
| Total | ₹1,68,000 | ₹14,000 |
In this example, the family does not really have ₹1.68 lakh of occasional expenses. It has a ₹14,000 monthly commitment that happens to be billed at different times.
That change in perspective is important. It reveals the family’s true monthly cost of living and prevents the budget from looking artificially comfortable during months without a large bill.
If the payment is due soon, divide by the months remaining
Dividing the annual total by 12 works well when planning for the next full year. But if a ₹60,000 school payment is due six months from now and nothing has been saved, the required provision is ₹10,000 per month—not ₹5,000.
Use this simple formula for each upcoming bill:
Amount still required ÷ months remaining before the due date = monthly amount to set aside
After the first payment cycle is completed, continue saving every month. The following year’s bill should then be funded over a full 12 months.
Keep an annual expense fund separate
The monthly provision should preferably move out of the regular spending account soon after income is received. A separate bank account or clearly labelled savings bucket can make the money less likely to be spent accidentally.
For money needed within the next year, the priorities are:
- Safety of the amount set aside
- Easy access before the due date
- Low risk of a loss when the money is required
A savings account or recurring deposit may be suitable depending on the due dates and need for flexibility. Some investors may consider very short-term debt products, but these are market-linked and should not be treated as guaranteed bank deposits. Equity funds are generally unsuitable for bills due in the near term because their value can fall precisely when the payment is required.
The objective of this fund is not to maximise returns. It is to make the household’s cash flow reliable.
Annual expense fund versus emergency fund
These two funds solve different problems and should not be mixed.
| Question | Annual expense fund | Emergency fund |
|---|---|---|
| What is it for? | Known bills such as fees, premiums and renewals | Unexpected events such as job loss or urgent repairs |
| Is the timing known? | Usually yes | No |
| Should regular use be expected? | Yes, as bills become due | Only when a genuine emergency occurs |
| How is it replenished? | Through a planned monthly provision | Rebuilt after an emergency withdrawal |
Using the emergency fund for an annual school fee weakens the household’s protection. The payment may feel large, but it was known in advance and should have been funded separately.
Do not stop SIPs whenever a large bill arrives
Pausing a SIP once may appear harmless. But when school fees, insurance, travel and other annual bills are handled this way, long-term investments can be interrupted repeatedly.
The better order is:
- Include predictable annual expenses while calculating the monthly household surplus.
- Set aside their monthly provision.
- Decide the sustainable amount available for SIPs and other goals.
A slightly smaller SIP that continues consistently is better than an unrealistic SIP that must be stopped whenever a known payment appears.
Review the list once a year
An annual expense plan should not be copied without review. Before beginning the next cycle:
- Update school fees and education-related costs
- Check renewal notices for insurance premiums
- Remove subscriptions or memberships you no longer intend to use
- Add expenses that were missed last year
- Increase estimates where inflation or usage has raised the cost
- Verify that each insurance policy is still appropriate instead of renewing it automatically
The last point matters. Setting aside money for a premium solves the cash-flow problem; it does not prove that the policy itself remains suitable.
A simple annual-expense worksheet
Create a sheet with these five columns:
| Expense | Due month | Expected amount | Already saved | Monthly provision required |
|---|---|---|---|---|
Once the total monthly provision is known, automate a transfer for that amount. Planning becomes much easier when the decision does not have to be repeated every month.
Frequently asked questions
Is an annual expense fund the same as a sinking fund?
Yes. A sinking fund is money accumulated gradually for a known future expense. “Annual expense fund” is simply a more descriptive name for household use.
Should each expense have a separate account?
Not necessarily. One separate account can hold the combined annual-expense fund, provided you maintain a simple record of how much is reserved for each bill.
What if the exact amount is unknown?
Use the previous amount, add a reasonable buffer and update the estimate when the actual bill becomes available. An approximate plan is better than waiting for perfect information.
Should bonuses be used for annual expenses?
A bonus can help create the fund initially, but recurring and unavoidable expenses should ideally be supported by regular monthly income. Depending on an uncertain bonus for a compulsory bill can create a future shortfall.
What happens to money left over at the end of the year?
Keep it in the fund for the next cycle or allocate it deliberately to another goal. Do not treat it as accidental spending money until all upcoming bills are covered.
The takeaway
An expense does not become an emergency merely because it is large or paid only once a year.
School fees, uniforms, insurance premiums and renewals are part of the family’s true cost of living. When they are converted into monthly provisions, the household can pay them on time without relying on credit, weakening the emergency fund or repeatedly interrupting long-term investments.
The simplest rule is:
If you know that a bill will arrive, start paying your future self for it every month.
This article is for educational purposes and does not constitute investment, insurance or tax advice. Product suitability depends on individual circumstances.