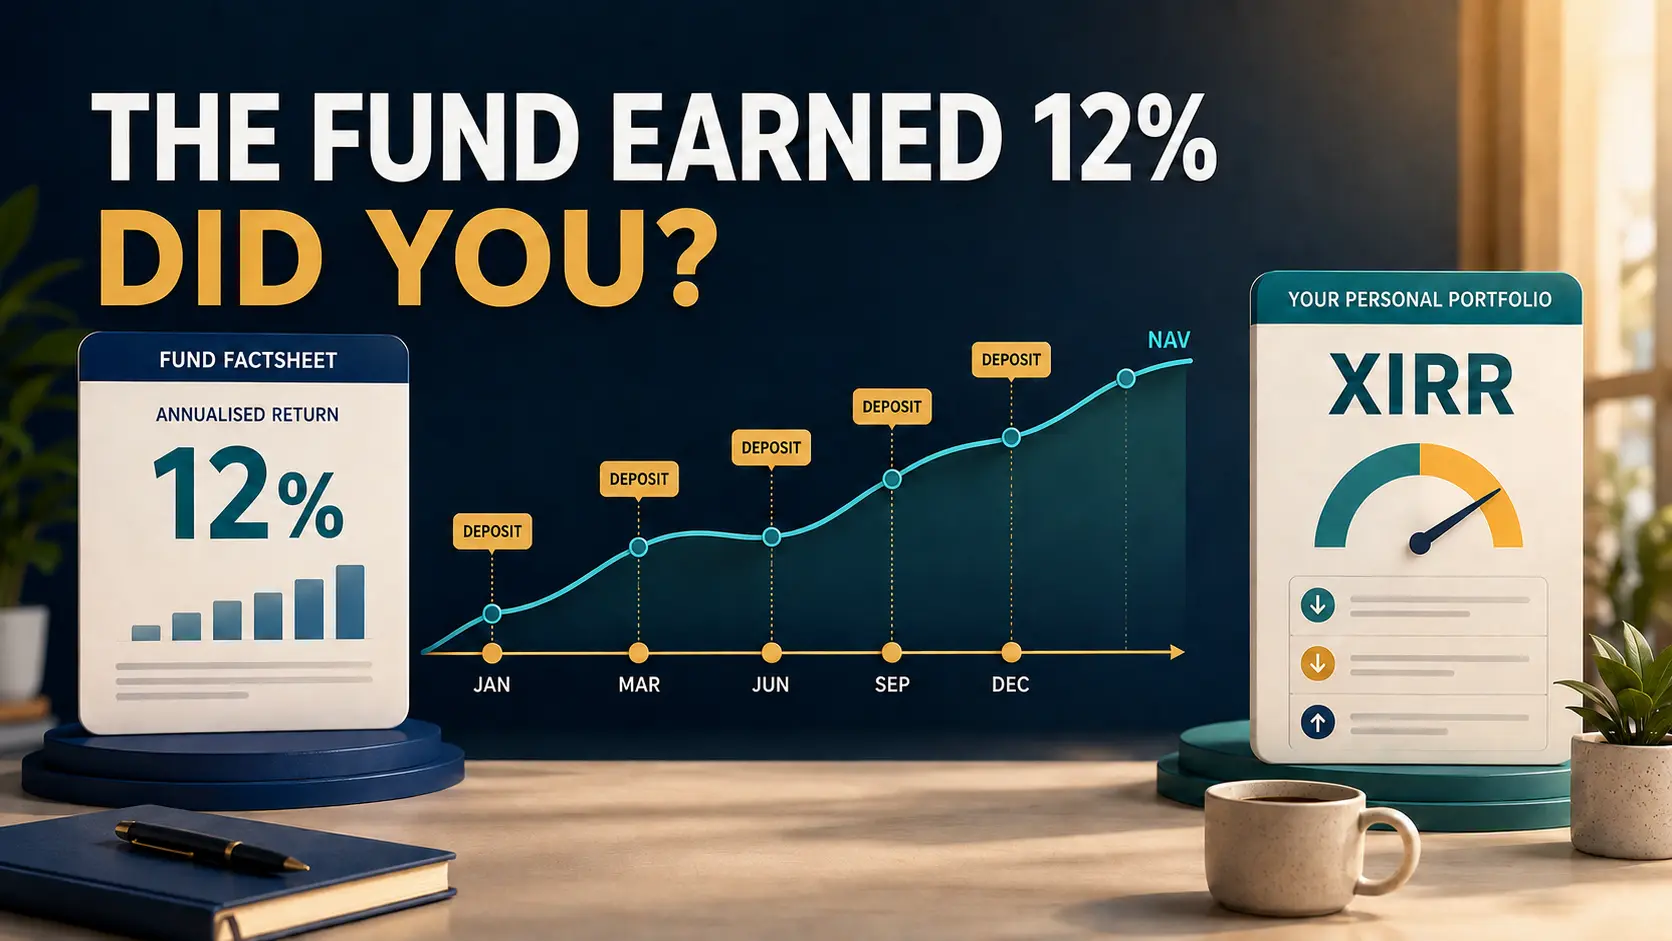
A mutual fund page may say the fund returned 12%. Your statement may show a different number. Both figures can be correct. They answer different questions.
The fund’s reported return measures its performance over a stated period. Your own return also depends on when you invested, how much you added and when you took money out.
One payment or many?
For one investment held over several years, CAGR shows the annual rate that would link its starting value to its ending value. The actual year-by-year return was not necessarily steady.
For a SIP, money enters on different dates. A ₹5,000 instalment invested three years ago had more time in the market than one invested last month. A single start-to-end fund return cannot describe both instalments.
XIRR is an annualised return that takes account of the date and size of each payment and withdrawal. It is commonly used for a SIP or a portfolio with several transactions. It reflects the cash flows you actually made, based on the values and dates included in the calculation.
| Question | Useful measure |
|---|---|
| How did the fund do over a stated period? | The fund’s reported period return, with the period and plan stated. |
| How did my single investment do each year on average? | CAGR, if there were no other cash flows. |
| How did my SIP or changing portfolio do? | XIRR, with all relevant payments, withdrawals and current value included. |
Why your number can differ
Imagine two people who own the same fund. One invested a lump sum before a market fall. The other added money each month through the fall. Their purchase dates and prices differ. So their personal returns can differ, even though they hold the same scheme.
Your app and statement may also show different figures. Check the dates, the valuation used and whether both include every purchase, switch and withdrawal. A recent transaction or a short holding period can make an annualised figure swing sharply.
Does a high XIRR mean you chose well?
Not by itself. An investor may have added money near a market low by chance. A strong XIRR may also cover only a short period. Neither proves that the fund is suitable for a family goal or that the result will continue.
Likewise, you cannot fairly compare your SIP’s XIRR with a benchmark’s simple start-to-end return. The investment dates differ. If you need a like-for-like comparison, ask for the benchmark return calculated using the same cash flows and dates.
One number cannot measure the value of an adviser or distributor either. Good support may include keeping the plan suitable, helping a family stay invested through difficult periods and making sure the money is available when needed. Those outcomes need a broader review.
What should you ask at a review?
Ask which period and plan the fund’s published figure uses. Ask whether your personal XIRR includes all transactions. Then look beyond the percentage: Is the goal on track? Has the level of risk changed? Will the money be needed soon?
Takeaway: Use a fund’s reported return to understand the scheme. Use your XIRR to understand the effect of your own cash flows. Neither should replace a review of the goal, risk and time left.
Examples here explain measures, not expected returns. Returns can be negative; past returns do not promise future results. Check the current fund factsheet and transaction record before relying on a displayed figure.