Category: Mutual Funds

  • Small-Cap SIP Assets Have Grown 5x: Should You Increase Yours?

    Small-Cap SIP Assets Have Grown 5x: Should You Increase Yours?

    Small-cap mutual funds have attracted significant SIP money over the
    past five years.

    According to the AMFI–Crisil Factbook 2026, SIP
    assets in small-cap funds increased from ₹35,489 crore in March
    2021 to ₹1,83,069 crore in March 2026
    . That is an increase of
    approximately 5.2 times in five years.

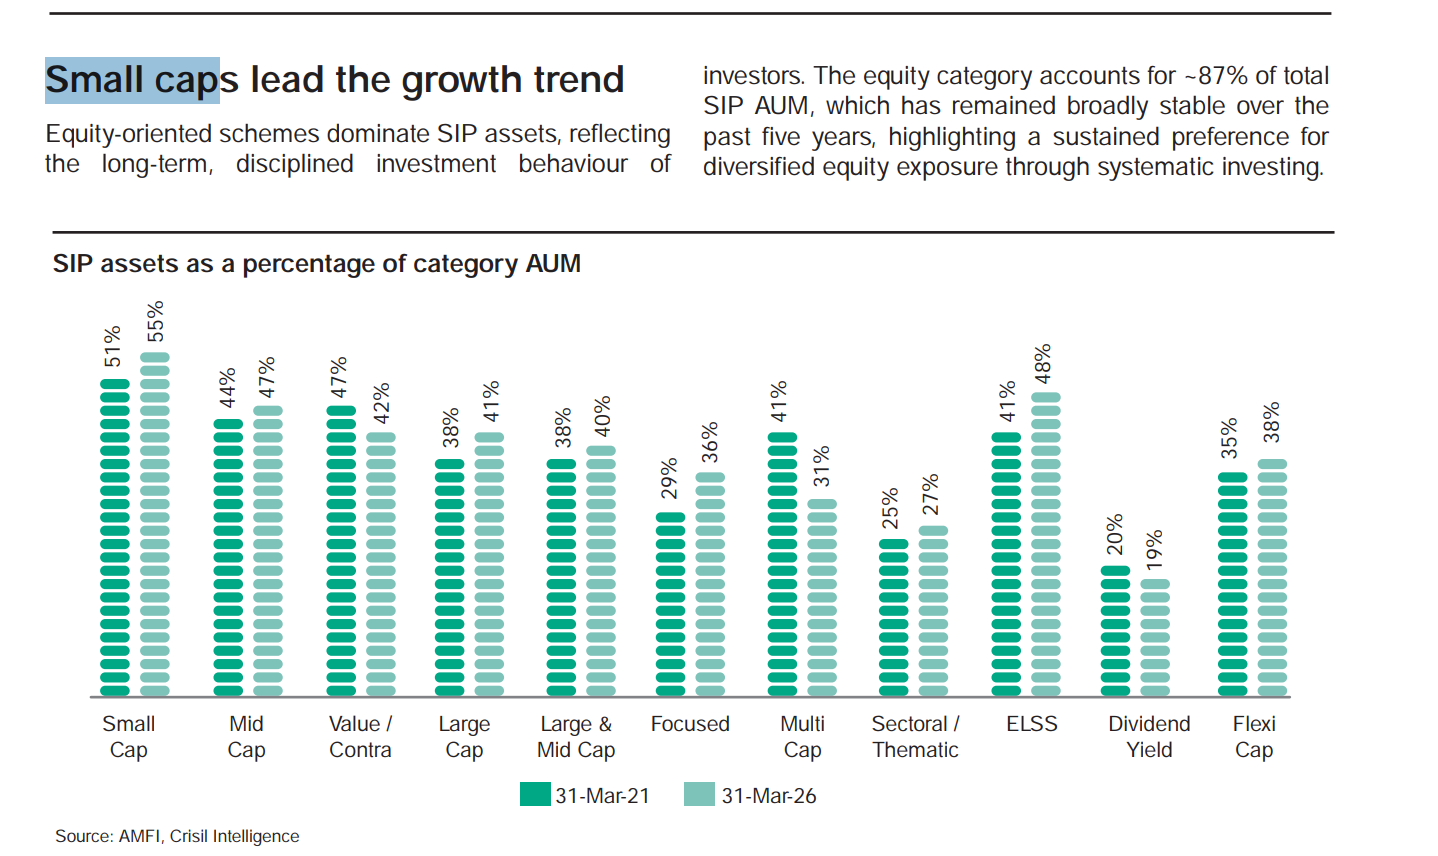
    The report also states that SIP assets represented 55% of the
    total assets in the small-cap fund category
    as of March
    2026—the highest proportion among the equity-fund categories shown in
    the report.

    These figures demonstrate how strongly investors have embraced
    small-cap SIPs. But do they also mean that you should increase
    yours?

    Not necessarily.

    The growth of an investment category tells us where investors have
    been putting their money. It does not tell us whether that category is
    attractively valued today, whether it will outperform next, or whether
    it is suitable for a particular investor.

    What Does the 55% Figure
    Actually Mean?

    The 55% figure can easily be misunderstood.

    It does not mean that small-cap funds received 55%
    of all SIP investments in India. It also does not represent a return
    earned by investors.

    It means that, as of March 2026, the value of assets accumulated
    through SIPs in small-cap schemes accounted for approximately
    55% of the total AUM of the small-cap fund
    category
    .

    The same chart shows that this proportion was 51% in March 2021. The
    increase from 51% to 55% is meaningful, but the much larger change is
    visible in the absolute SIP assets accumulated in the category.

    The factbook’s category table shows:

    Small-cap SIP data March 2021 March 2026
    SIP AUM ₹35,489 crore ₹1,83,069 crore
    Share of total industry SIP AUM 8.3% 12.1%

    Therefore, the accurate conclusion is:

    Small-cap SIP assets grew by approximately 5.2
    times—not necessarily the total AUM of small-cap funds and certainly not
    investor returns.
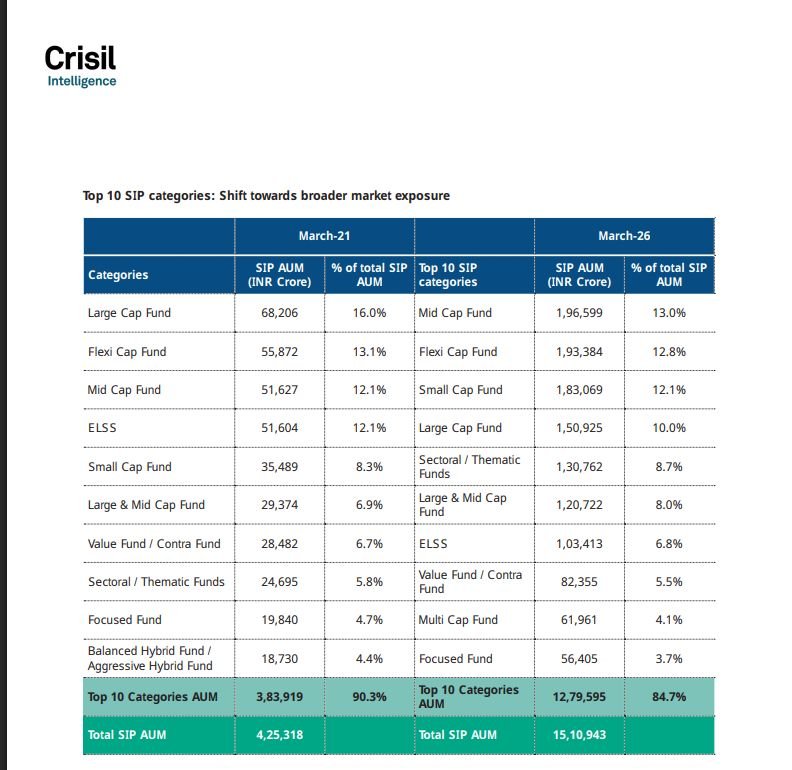
    AMFI-Crisil table showing small-cap SIP AUM increasing from ₹35,489 crore in March 2021 to ₹1,83,069 crore in March 2026.
    Leading mutual-fund categories by SIP AUM in March 2021 and March 2026. Source: AMFI-Crisil Factbook 2026.

    Why Have Small-Cap
    SIP Assets Grown So Much?

    The increase is likely the result of several forces acting
    together:

    • More investors have entered mutual funds through monthly SIPs.
    • Strong historical periods for smaller companies attracted investor
      attention.
    • Investment platforms have made starting and managing SIPs
      easier.
    • Small monthly investments can make a volatile category feel more
      approachable.
    • Investors increasingly associate small-cap companies with higher
      long-term growth potential.

    However, a category often becomes most popular after
    it has delivered attractive returns. This can encourage investors to
    increase exposure based on recent performance rather than their
    financial plan.

    That is why rising SIP participation should be treated as a trend to
    understand—not as a buy signal.

    A SIP
    Changes How You Invest, Not What You Invest In

    A SIP spreads investments across different market levels instead of
    committing the entire amount on one day. This can reduce the risk of
    investing a large lump sum at an unfavourable time and helps build
    investing discipline.

    But a SIP does not remove the underlying risk of the asset.

    If small-cap stocks decline sharply, a small-cap fund can also
    experience a substantial fall. Continuing the SIP during that period may
    allow the investor to accumulate more units at lower NAVs, but the
    portfolio value can still remain below the invested amount for an
    extended period.

    A SIP therefore does not:

    • guarantee positive returns;
    • prevent short-term or medium-term losses;
    • make every fund suitable for every investor;
    • compensate for an excessive small-cap allocation; or
    • turn a short investment horizon into a long one.

    The discipline of a SIP is valuable only when the investor can remain
    invested through the category’s difficult periods.

    Why Small-Cap Funds Need
    More Patience

    Under the mutual-fund categorisation framework, small-cap companies
    are generally those ranked 251st onwards by full market
    capitalisation
    . A small-cap fund is required to invest at least
    65% of its assets in small-cap stocks.

    Compared with established large companies, smaller companies may
    have:

    • less diversified businesses;
    • lower trading liquidity;
    • greater dependence on a few customers or products;
    • more sensitivity to economic slowdowns;
    • limited ability to raise capital during difficult periods; and
    • wider differences between successful and unsuccessful
      businesses.

    This does not make small-cap funds unsuitable. It means that the
    potential for higher growth comes with greater uncertainty, deeper
    volatility and the possibility of prolonged underperformance.

    An investor who needs the money in three or five years may not have
    enough time to wait for the category to recover from an unfavourable
    market cycle. Small-cap exposure is generally more appropriate for goals
    that are at least seven to ten years away, with the
    understanding that even a long horizon does not guarantee a particular
    return.

    Should You Increase Your
    Small-Cap SIP?

    The answer should depend on your allocation—not on the industry’s
    growth statistics.

    Consider increasing it only
    when:

    • your financial goal is sufficiently long-term;
    • your emergency fund and near-term requirements are already
      covered;
    • small caps currently form less than your planned allocation;
    • you understand the small-cap exposure already present in your
      flexicap, multicap or other equity funds;
    • you can continue investing through a sharp decline; and
    • the increase is part of a portfolio plan rather than a response to
      recent returns.

    Maintain the existing SIP
    when:

    • the current allocation is already close to your target;
    • the SIP amount remains appropriate for the goal;
    • your risk capacity and time horizon have not changed; and
    • recent category popularity is the only reason you are considering an
      increase.

    Consider reducing or
    redirecting it when:

    • small caps have become an excessive part of your equity
      portfolio;
    • you hold several small-cap funds with substantial portfolio
      overlap;
    • an important goal is getting closer;
    • market falls are causing you to stop or frequently change SIPs;
      or
    • you selected the category mainly because it had recently delivered
      high returns.

    Measure
    Small-Cap Exposure Across the Entire Portfolio

    Looking only at the fund named “Small Cap” can understate your actual
    exposure.

    Flexicap, multicap, focused, value and some thematic funds may also
    hold small-cap stocks. If you own several such schemes, your total
    small-cap exposure can be higher than expected.

    For example, suppose equity represents 70% of your overall investment
    portfolio and you decide that small caps should represent 15% of the
    equity portion.

    Your small-cap allocation at the total-portfolio level would be:

    70% × 15% = 10.5% of the overall portfolio

    The correct comparison is between this target and your combined
    small-cap exposure across every fund—not merely the value of your
    dedicated small-cap scheme.

    A Practical Way to
    Manage the Allocation

    Instead of changing the SIP based on headlines, use a simple
    process:

    1. Identify the goal: Confirm when the money will be
      required.
    2. Calculate existing exposure: Include small-cap
      holdings inside all equity schemes.
    3. Set a target range: Use a range rather than
      expecting the allocation to remain at one exact percentage.
    4. Direct new SIPs thoughtfully: Add money to an
      underweight category instead of automatically choosing the recent
      winner.
    5. Review periodically: Review annually or when the
      allocation moves materially outside its target—not every time markets
      fluctuate.

    This approach turns the decision from “Are small-cap funds doing
    well?” into the more useful question: “Does my current allocation still
    suit my goal and my ability to handle risk?”

    The Takeaway

    The rise of small-cap SIP assets from ₹35,489 crore to ₹1,83,069
    crore is a significant change in Indian investor behaviour. It shows
    that SIPs have become an important route for participating in small-cap
    funds.

    But popularity is not the same as suitability.

    A small-cap SIP can play a useful role in a diversified, long-term
    portfolio. Whether you should start, increase or maintain one depends on
    your goal, investment horizon, existing exposure and ability to remain
    invested through severe volatility.

    The AMFI–Crisil data gives us a reason to examine our allocation. It
    does not give everyone a reason to increase it.


    Sources

    This article is for educational purposes only and should not be
    treated as investment advice or a recommendation to invest in any
    particular mutual-fund scheme. Mutual-fund investments are subject to
    market risks. Read all scheme-related documents carefully and consider
    consulting a qualified financial professional before investing.
  • Multi Cap vs Flexi Cap Funds: What’s the Difference?

    Multi Cap vs Flexi Cap Funds: What’s the Difference?

    Multi Cap and Flexi Cap funds can both invest in large-cap, mid-cap and small-cap stocks.

    So why do we need two separate categories?

    The key difference is simple:

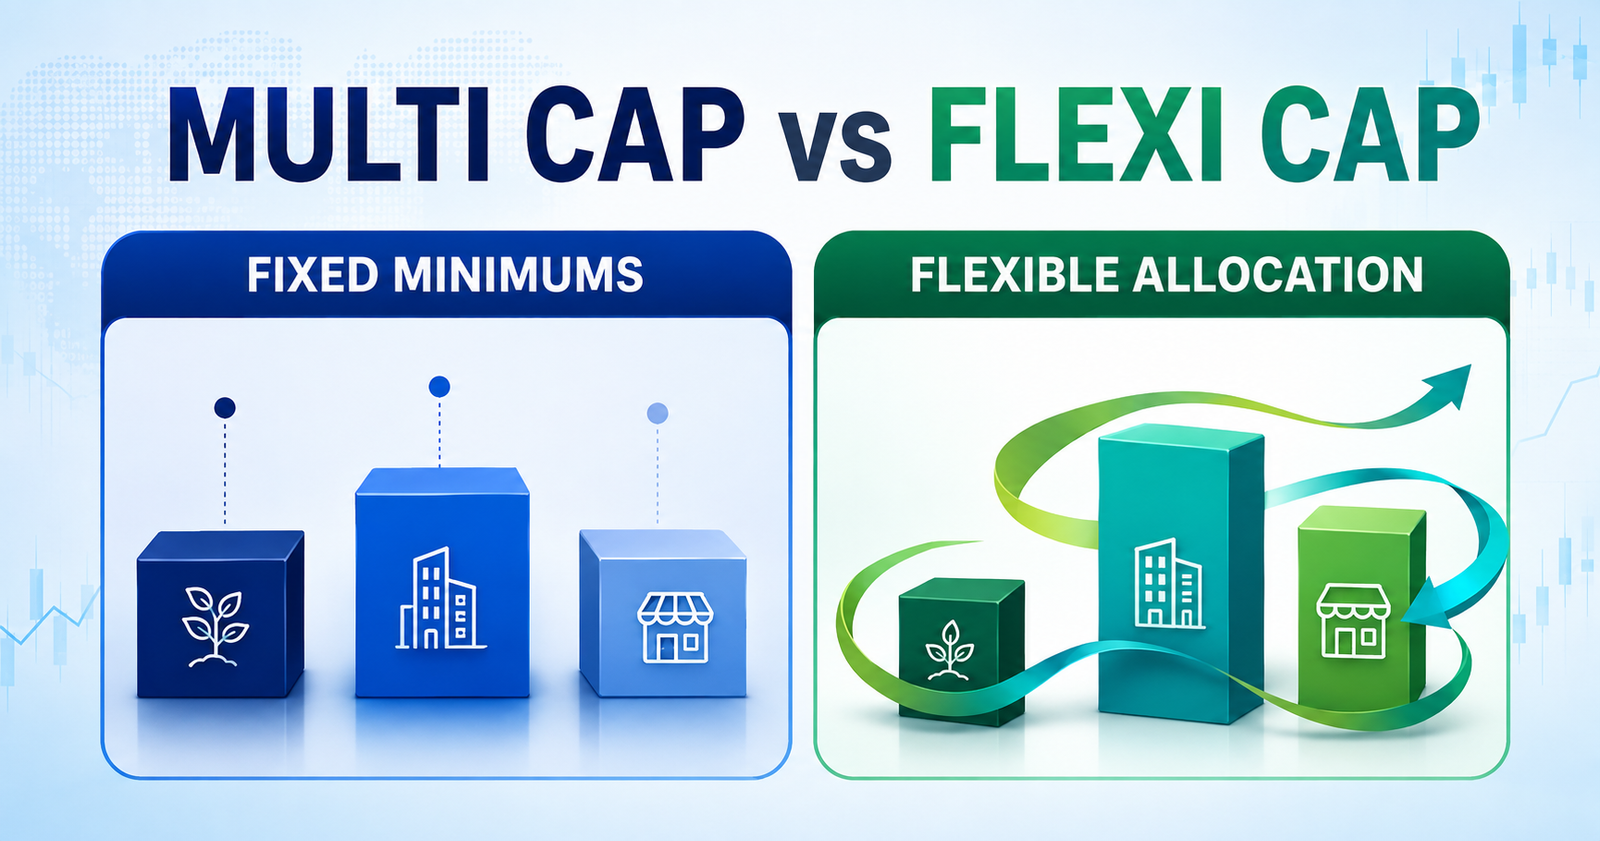
    Multi Cap funds follow fixed minimum allocation rules. Flexi Cap funds give the fund manager more freedom to decide how much to invest in each market-cap segment.

    That difference can significantly affect how the fund behaves in different market conditions.

    Multi Cap vs Flexi Cap: Quick Comparison

    Feature Multi Cap Fund Flexi Cap Fund
    Large-cap exposure Minimum 25% No fixed minimum
    Mid-cap exposure Minimum 25% No fixed minimum
    Small-cap exposure Minimum 25% No fixed minimum
    Fund manager flexibility Lower Higher
    Meaningful mid/small-cap exposure Built into the category Depends on fund manager
    Can become heavily large-cap oriented No Yes
    Risk level Usually higher due to mandatory mid/small-cap exposure Depends on actual portfolio

    The easiest way to remember it is:

    Multi Cap = Allocation

    Flexi Cap = Flexibility

    What Is a Multi Cap Fund?

    A Multi Cap Fund must invest at least:

    • 25% in large-cap stocks
    • 25% in mid-cap stocks
    • 25% in small-cap stocks

    This means the fund always has meaningful exposure across all three market-cap segments.

    That can be useful for investors who want one fund that gives them exposure to the broader equity market.

    But there is an important trade-off.

    Even if mid-cap or small-cap valuations become expensive, the fund manager cannot completely move away from those segments.

    So a Multi Cap fund may experience higher volatility when mid- and small-cap stocks fall sharply.

    What Is a Flexi Cap Fund?

    A Flexi Cap Fund can also invest across large-, mid- and small-cap companies.

    The difference is that there is no fixed minimum allocation to each market-cap segment.

    The fund manager can decide where the best opportunities are.

    For example, a Flexi Cap fund could hold:

    • 75% Large Cap
    • 15% Mid Cap
    • 10% Small Cap

    At another point, the same fund could move to:

    • 50% Large Cap
    • 30% Mid Cap
    • 20% Small Cap

    This gives the manager more flexibility to respond to valuations and market conditions.

    A Simple Example

    Suppose mid-cap and small-cap stocks have gone through a strong rally and now look expensive.

    A Flexi Cap manager may decide to reduce exposure to those segments and increase large-cap allocation.

    A Multi Cap manager cannot do the same beyond a point because the fund must continue to maintain at least 25% in both mid- and small-cap stocks.

    This is the core difference between the two categories.

    A Multi Cap fund guarantees diversification across market caps. A Flexi Cap fund gives the manager freedom to decide the diversification.

    Is Flexi Cap Better?

    Not necessarily.

    Flexibility can be useful, but it also means the fund manager’s decisions matter more.

    If the manager reduces mid- and small-cap exposure before those segments rally strongly, the fund may underperform a Multi Cap fund.

    Likewise, if the manager correctly avoids an expensive market segment before a fall, that flexibility may help.

    So Flexi Cap is not automatically safer or better.

    Its behaviour depends on the actual portfolio.

    Is Multi Cap Better?

    Again, not necessarily.

    Multi Cap works well for investors who specifically want meaningful exposure to large-, mid- and small-cap companies.

    The advantage is that the fund cannot quietly become almost entirely large-cap.

    The disadvantage is that the fund cannot substantially reduce mid- or small-cap exposure during difficult market conditions.

    So Multi Cap is better viewed as a structured all-market allocation, rather than simply a more aggressive version of Flexi Cap.

    Who May Prefer a Multi Cap Fund?

    A Multi Cap fund may suit you if you:

    • Want meaningful exposure to large, mid and small companies
    • Prefer market-cap diversification to be built into the fund
    • Have a long investment horizon
    • Are comfortable with higher equity volatility
    • Do not want allocation decisions to depend entirely on the fund manager

    Who May Prefer a Flexi Cap Fund?

    A Flexi Cap fund may suit you if you:

    • Prefer the fund manager to have greater flexibility
    • Want one diversified equity fund without fixed market-cap weights
    • Already have separate mid-cap or small-cap funds
    • Want the manager to reduce exposure to unattractive market segments when necessary

    Can You Invest in Both?

    Yes, but that does not automatically improve diversification.

    For example, if you already hold:

    • A Flexi Cap fund
    • A Mid Cap fund
    • A Small Cap fund

    adding a Multi Cap fund may further increase your mid- and small-cap exposure.

    The better question is not:

    “Can I invest in both?”

    It is:

    “What role does each fund play in my overall portfolio?”

    Always look at your total asset allocation rather than choosing mutual funds one category at a time.

    Don’t Choose Based Only on Recent Returns

    A Multi Cap fund may outperform during a strong mid- and small-cap rally simply because it is required to maintain meaningful exposure to those segments.

    A Flexi Cap fund with a large-cap-heavy portfolio may lag during the same period.

    That does not necessarily mean one fund is better than the other.

    Before comparing funds, look at:

    • Portfolio allocation
    • Risk taken
    • Rolling returns
    • Drawdowns
    • Consistency
    • Investment style
    • Role in your overall portfolio

    Returns make more sense when viewed together with the risk taken to generate them.

    Final Takeaway

    Multi Cap and Flexi Cap funds invest across the same broad market-cap universe, but their portfolio construction is different.

    Multi Cap

    • Minimum 25% Large Cap
    • Minimum 25% Mid Cap
    • Minimum 25% Small Cap

    Best understood as a fund with built-in market-cap diversification.

    Flexi Cap

    No fixed allocation between large, mid and small caps

    Best understood as a fund that gives the manager greater allocation flexibility.

    Neither category is automatically better.

    The right choice depends on your:

    • Existing portfolio
    • Risk tolerance
    • Investment horizon
    • Need for mid- and small-cap exposure
    • Preference for structured allocation versus fund-manager flexibility

    The most important thing is to understand what role the fund is expected to play in your overall portfolio.

    Frequently Asked Questions

    Is Multi Cap riskier than Flexi Cap?

    Multi Cap funds have mandatory exposure to mid- and small-cap stocks, which can make them more volatile. Flexi Cap risk depends on how the fund manager actually allocates the portfolio.

    Can a Flexi Cap fund invest mostly in large caps?

    Yes. A Flexi Cap fund does not have a fixed minimum allocation to mid- or small-cap stocks.

    Can a Multi Cap fund reduce small-cap exposure when valuations are high?

    It can reduce exposure only up to the regulatory minimum. It must continue to maintain at least 25% in small-cap stocks.

    Should I hold both Multi Cap and Flexi Cap funds?

    You can, but first check whether doing so creates unnecessary overlap or excessive mid- and small-cap exposure.

    Disclaimer

    This article is for educational purposes only and should not be considered investment advice or a recommendation to invest in any particular mutual fund or category. Mutual fund investments are subject to market risks. Consider your financial goals, investment horizon and risk profile before investing.