
Small-cap mutual funds have attracted significant SIP money over the
past five years.
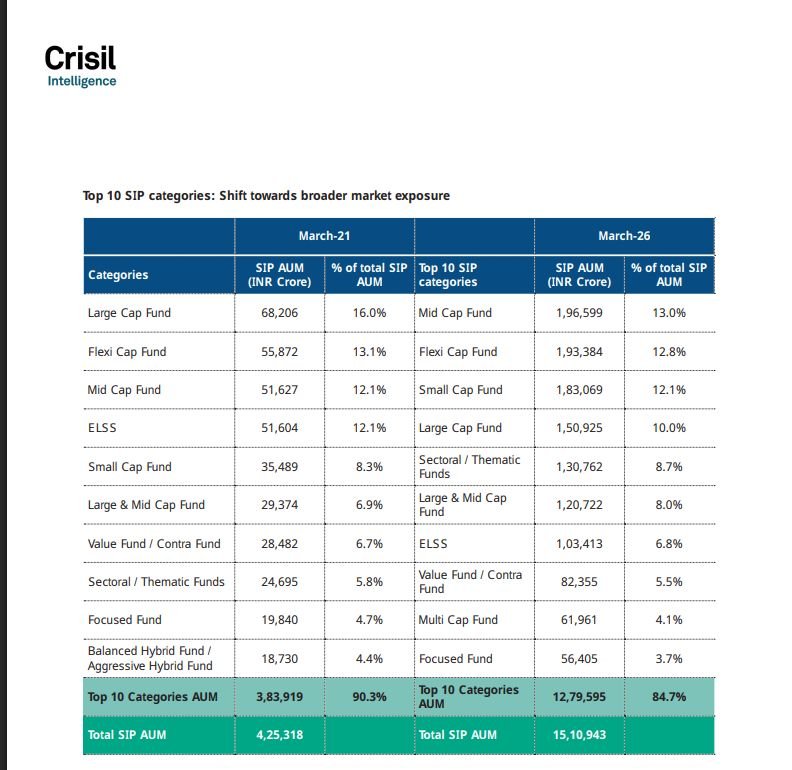
According to the AMFI–Crisil Factbook 2026, SIP
assets in small-cap funds increased from ₹35,489 crore in March
2021 to ₹1,83,069 crore in March 2026. That is an increase of
approximately 5.2 times in five years.
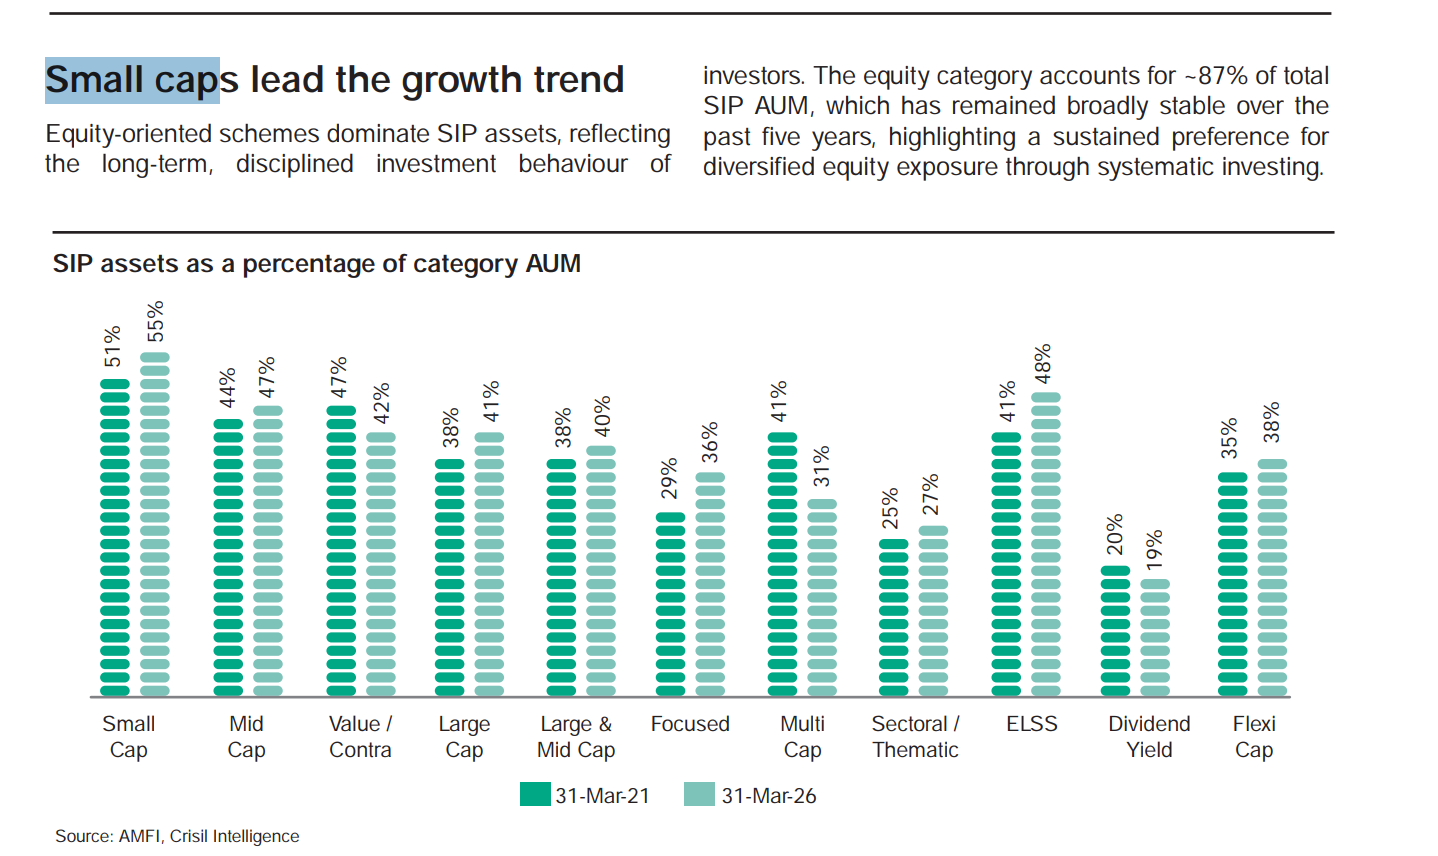
The report also states that SIP assets represented 55% of the
total assets in the small-cap fund category as of March
2026—the highest proportion among the equity-fund categories shown in
the report.
These figures demonstrate how strongly investors have embraced
small-cap SIPs. But do they also mean that you should increase
yours?
Not necessarily.
The growth of an investment category tells us where investors have
been putting their money. It does not tell us whether that category is
attractively valued today, whether it will outperform next, or whether
it is suitable for a particular investor.
What Does the 55% Figure
Actually Mean?
The 55% figure can easily be misunderstood.
It does not mean that small-cap funds received 55%
of all SIP investments in India. It also does not represent a return
earned by investors.
It means that, as of March 2026, the value of assets accumulated
through SIPs in small-cap schemes accounted for approximately
55% of the total AUM of the small-cap fund
category.
The same chart shows that this proportion was 51% in March 2021. The
increase from 51% to 55% is meaningful, but the much larger change is
visible in the absolute SIP assets accumulated in the category.
The factbook’s category table shows:
| Small-cap SIP data | March 2021 | March 2026 |
|---|---|---|
| SIP AUM | ₹35,489 crore | ₹1,83,069 crore |
| Share of total industry SIP AUM | 8.3% | 12.1% |
Therefore, the accurate conclusion is:
Small-cap SIP assets grew by approximately 5.2
times—not necessarily the total AUM of small-cap funds and certainly not
investor returns.
Why Have Small-Cap
SIP Assets Grown So Much?
The increase is likely the result of several forces acting
together:
- More investors have entered mutual funds through monthly SIPs.
- Strong historical periods for smaller companies attracted investor
attention. - Investment platforms have made starting and managing SIPs
easier. - Small monthly investments can make a volatile category feel more
approachable. - Investors increasingly associate small-cap companies with higher
long-term growth potential.
However, a category often becomes most popular after
it has delivered attractive returns. This can encourage investors to
increase exposure based on recent performance rather than their
financial plan.
That is why rising SIP participation should be treated as a trend to
understand—not as a buy signal.
A SIP
Changes How You Invest, Not What You Invest In
A SIP spreads investments across different market levels instead of
committing the entire amount on one day. This can reduce the risk of
investing a large lump sum at an unfavourable time and helps build
investing discipline.
But a SIP does not remove the underlying risk of the asset.
If small-cap stocks decline sharply, a small-cap fund can also
experience a substantial fall. Continuing the SIP during that period may
allow the investor to accumulate more units at lower NAVs, but the
portfolio value can still remain below the invested amount for an
extended period.
A SIP therefore does not:
- guarantee positive returns;
- prevent short-term or medium-term losses;
- make every fund suitable for every investor;
- compensate for an excessive small-cap allocation; or
- turn a short investment horizon into a long one.
The discipline of a SIP is valuable only when the investor can remain
invested through the category’s difficult periods.
Why Small-Cap Funds Need
More Patience
Under the mutual-fund categorisation framework, small-cap companies
are generally those ranked 251st onwards by full market
capitalisation. A small-cap fund is required to invest at least
65% of its assets in small-cap stocks.
Compared with established large companies, smaller companies may
have:
- less diversified businesses;
- lower trading liquidity;
- greater dependence on a few customers or products;
- more sensitivity to economic slowdowns;
- limited ability to raise capital during difficult periods; and
- wider differences between successful and unsuccessful
businesses.
This does not make small-cap funds unsuitable. It means that the
potential for higher growth comes with greater uncertainty, deeper
volatility and the possibility of prolonged underperformance.
An investor who needs the money in three or five years may not have
enough time to wait for the category to recover from an unfavourable
market cycle. Small-cap exposure is generally more appropriate for goals
that are at least seven to ten years away, with the
understanding that even a long horizon does not guarantee a particular
return.
Should You Increase Your
Small-Cap SIP?
The answer should depend on your allocation—not on the industry’s
growth statistics.
Consider increasing it only
when:
- your financial goal is sufficiently long-term;
- your emergency fund and near-term requirements are already
covered; - small caps currently form less than your planned allocation;
- you understand the small-cap exposure already present in your
flexicap, multicap or other equity funds; - you can continue investing through a sharp decline; and
- the increase is part of a portfolio plan rather than a response to
recent returns.
Maintain the existing SIP
when:
- the current allocation is already close to your target;
- the SIP amount remains appropriate for the goal;
- your risk capacity and time horizon have not changed; and
- recent category popularity is the only reason you are considering an
increase.
Consider reducing or
redirecting it when:
- small caps have become an excessive part of your equity
portfolio; - you hold several small-cap funds with substantial portfolio
overlap; - an important goal is getting closer;
- market falls are causing you to stop or frequently change SIPs;
or - you selected the category mainly because it had recently delivered
high returns.
Measure
Small-Cap Exposure Across the Entire Portfolio
Looking only at the fund named “Small Cap” can understate your actual
exposure.
Flexicap, multicap, focused, value and some thematic funds may also
hold small-cap stocks. If you own several such schemes, your total
small-cap exposure can be higher than expected.
For example, suppose equity represents 70% of your overall investment
portfolio and you decide that small caps should represent 15% of the
equity portion.
Your small-cap allocation at the total-portfolio level would be:
70% × 15% = 10.5% of the overall portfolio
The correct comparison is between this target and your combined
small-cap exposure across every fund—not merely the value of your
dedicated small-cap scheme.
A Practical Way to
Manage the Allocation
Instead of changing the SIP based on headlines, use a simple
process:
- Identify the goal: Confirm when the money will be
required. - Calculate existing exposure: Include small-cap
holdings inside all equity schemes. - Set a target range: Use a range rather than
expecting the allocation to remain at one exact percentage. - Direct new SIPs thoughtfully: Add money to an
underweight category instead of automatically choosing the recent
winner. - Review periodically: Review annually or when the
allocation moves materially outside its target—not every time markets
fluctuate.
This approach turns the decision from “Are small-cap funds doing
well?” into the more useful question: “Does my current allocation still
suit my goal and my ability to handle risk?”
The Takeaway
The rise of small-cap SIP assets from ₹35,489 crore to ₹1,83,069
crore is a significant change in Indian investor behaviour. It shows
that SIPs have become an important route for participating in small-cap
funds.
But popularity is not the same as suitability.
A small-cap SIP can play a useful role in a diversified, long-term
portfolio. Whether you should start, increase or maintain one depends on
your goal, investment horizon, existing exposure and ability to remain
invested through severe volatility.
The AMFI–Crisil data gives us a reason to examine our allocation. It
does not give everyone a reason to increase it.
Sources
- AMFI–Crisil
Factbook 2026, particularly pages 38 and 39. - AMFI:
Categorisation of Mutual Fund Schemes. - AMFI:
Categorisation of Large-, Mid- and Small-Cap Stocks.
This article is for educational purposes only and should not be
treated as investment advice or a recommendation to invest in any
particular mutual-fund scheme. Mutual-fund investments are subject to
market risks. Read all scheme-related documents carefully and consider
consulting a qualified financial professional before investing.
Leave a Reply